Prepared by Zywave, Inc. Copyright 2026.
Nonprofit industry trends to watch in 2026
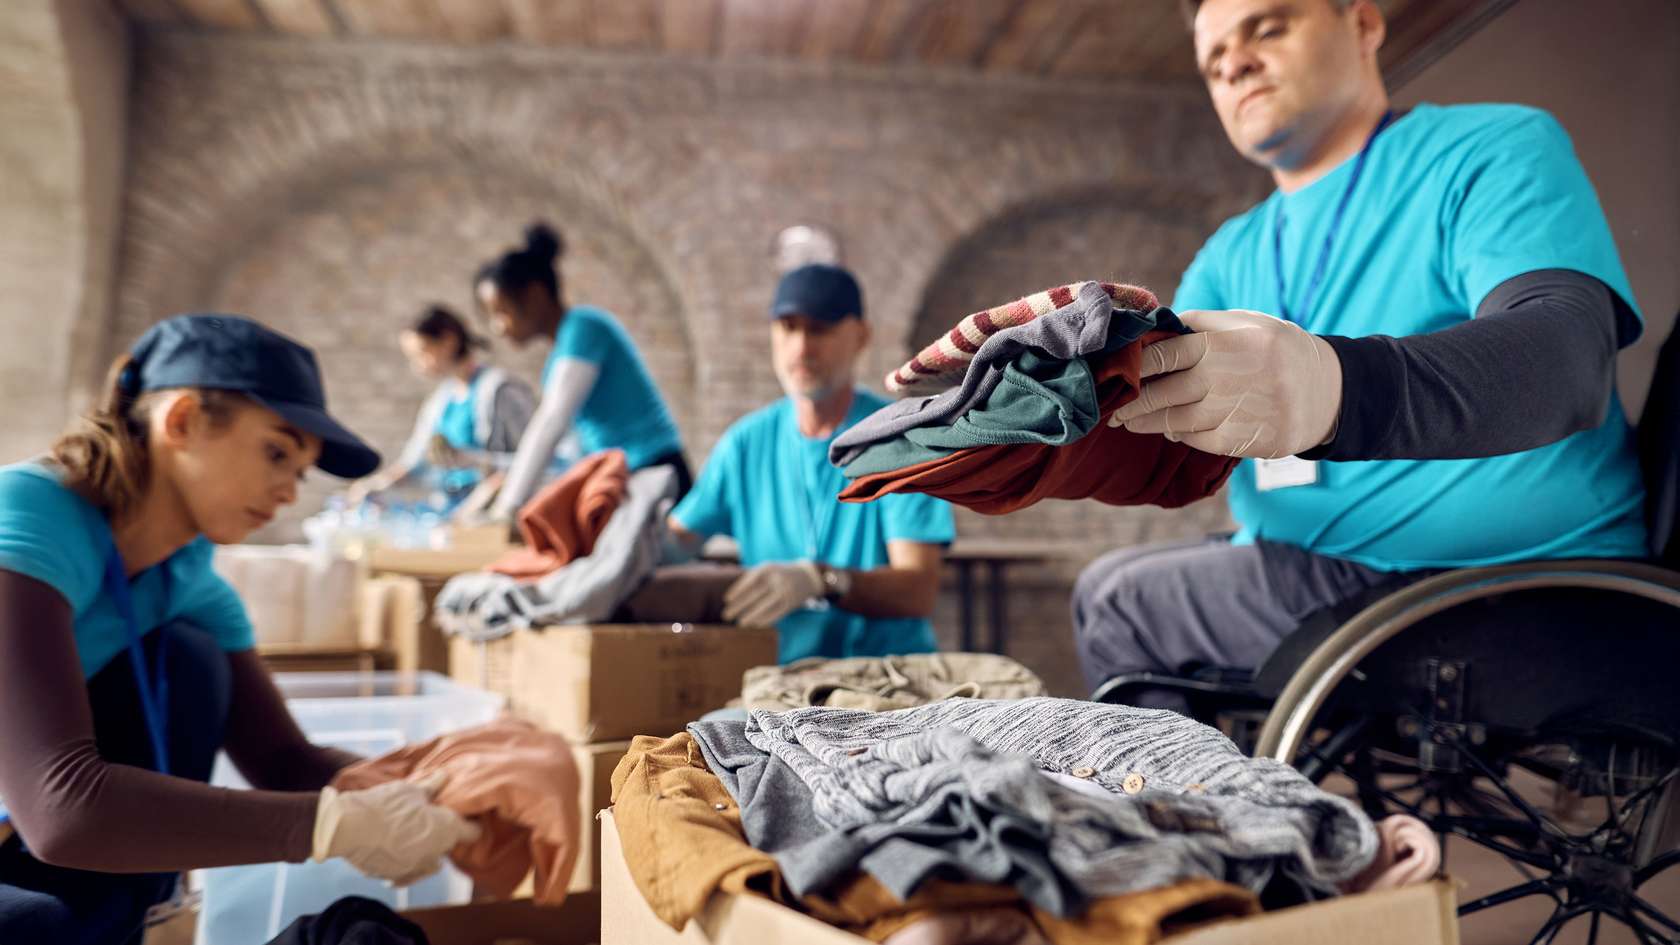
The nonprofit sector has been contending with a complex risk landscape for several years, largely fueled by economic uncertainty, funding pressures and rising demand for community outreach.
Amid these challenges, nonprofit organizations are facing significant operational and financial strains, making it harder to accomplish their missions and serve those in need. In the commercial insurance market, well-managed nonprofits have benefited from pricing moderation and ample capacity across multiple lines of coverage. However, most casualty lines and certain excess layers remain challenging, with insurers adopting more selective risk appetites and implementing strict underwriting standards, especially regarding proper governance and documentation.
In the current environment, several risks could undermine the sector’s future stability. As such, nonprofit organizations should monitor some emerging developments that may impact their operations and insurance portfolios this year—including funding volatility, cybercrime, regulatory scrutiny, excess capacity constraints and workforce struggles—and adjust their risk management programs accordingly. This article outlines nonprofit sector trends to watch in 2026 and offers strategies to help navigate them.
Funding volatility
In light of continued inflationary pressures and economic uncertainty, many nonprofits are experiencing funding difficulties. This may cause them to overestimate their projected revenue growth and encounter tighter donor budgets, prompting a shift toward cost-cutting measures and stronger reserves.
Nevertheless, some cost controls could do more harm than good. For instance, nonprofit organizations may defer building maintenance and repairs at their commercial properties to lower costs; yet, doing so may allow minor issues to escalate into major losses, resulting in costly property and business interruption claims. Additionally, nonprofits that reduce staffing numbers to address budget limitations may face increased workers’ compensation and liability exposures, as remaining employees are forced to work longer hours and become more prone to fatigue-induced errors and accidents. Compounding concerns, funding volatility and related economic stressors can motivate stakeholders to apply greater scrutiny toward nonprofit leaders’ financial decisions, creating heightened directors and officers liability (D&O) risks.
To help combat financial strains and associated insurance implications, it’s essential for nonprofits to diversify their funding sources; engage in proper scenario-based budgeting and reserve planning; uphold effective property maintenance protocols, staffing levels and asset protection measures; and clearly document all leadership decisions to demonstrate strong financial oversight to insurers at policy renewals.
Cybercrime
Like other industries, the nonprofit sector is increasingly using technology to enhance operations. Popular devices and applications include cloud storage systems that hold important records and data, digital fundraising platforms, and artificial intelligence (AI)-equipped chatbots and data analytics tools designed to improve donor engagement. While this technology can be beneficial, it also poses serious cyber risks.
Nonprofit organizations have long been attractive targets for cybercrime due to their frequent collection and use of sensitive information, high-trust cultures and—in many cases—limited security budgets and related safeguards. As technology continues to evolve, the most prevalent cyberattack methods currently include ransomware incidents and social engineering scams, both of which can result in fraudulent wire transfers, prolonged operational disruptions and the exposure of confidential data. Making matters worse, many cybercriminals are leveraging AI to increase the scope and severity of these attacks, driving up losses for affected organizations.
In addition to incurring lasting financial and reputational damage from cyberattacks, nonprofits may also face costly cyber and commercial crime claims. Depending on the nature of certain cyberattack methods and specific policy wording, losses stemming from ransomware and social engineering incidents may even be subject to coverage exclusions or restricted by sublimits, resulting in substantial out-of-pocket expenses.
Going forward, it’s critical for nonprofits to bolster their cyber hygiene by implementing routine staff awareness training, multifactor authentication, secure data backups, strict wire transfer verification protocols and tested incident response plans. Documenting these measures and ensuring strong cybersecurity oversight among leadership can also help nonprofits secure favorable rates and policy terms and minimize possible coverage gaps, as insurers place greater emphasis on these controls during underwriting processes.
Regulatory scrutiny
Nonprofit organizations have faced increased regulatory scrutiny and compliance pressures in recent years, both at the state and federal levels. This scrutiny has primarily centered around topics such as international funding, data privacy, worker classifications, reporting integrity, and executive compensation and oversight. Industry leaders anticipate such scrutiny to continue in the year ahead, thus posing continued compliance concerns.
If nonprofits neglect to keep up with shifting legislation, they could encounter severe regulatory penalties, costly lawsuits and reputational losses. Such noncompliance could also result in various types of insurance claims. For example, unethical funding practices, misreporting incidents and executive oversight failures could prompt D&O claims. On the other hand, internal disputes over work conditions or classifications, along with associated whistleblower incidents, could result in employment practices liability (EPL) claims.
In response to growing regulatory scrutiny and insurance exposures, it’s best for nonprofits to promote proper executive oversight and governance, particularly as it pertains to financial and cybersecurity laws. Nonprofits may also benefit from working with trusted legal counsel to establish formal compliance calendars and documentation practices, thereby demonstrating effective governance controls to insurers during their underwriting reviews.
Excess capacity constraints
Despite some lines of coverage showing signs of moderation in the commercial insurance market, nonprofit organizations continue to face challenging conditions across the casualty space, mainly in the professional and sexual abuse and molestation (SAM) liability segments. Due to rising claims frequency and severity within these segments, many high-risk policyholders are being met with reduced capacity, strict sublimits and restrictive coverage terms, especially among excess layers. These capacity constraints can make nonprofit organizations more susceptible to underinsurance concerns and related financial fallout amid costly liability claims.
As a result of these capacity concerns, some nonprofits—namely those with increased professional and SAM liability exposures (e.g., youth programs, counseling centers, elder care facilities, emergency shelters and religious institutions)— are turning to the excess and surplus (E&S) space to obtain specialized coverage and ensure adequate protection. Besides exploring E&S solutions, it’s also vital for nonprofits to reduce their overall liability exposures by conducting in-depth background checks and providing proper training for all employees and volunteers; requiring adequate staff supervision during high-risk operations; creating documented abuse prevention programs; and establishing detailed vendor contracts that outline each party’s specific liabilities.
Workforce struggles
Labor shortages have been a pressing concern across industry lines for several years, and the nonprofit sector is no exception. Complicating matters, many nonprofit organizations already struggle to offer competitive salaries and benefits due to limited financial flexibility. Consequently, they are more likely to lose potential and existing employees and volunteers to higher-paying jobs in the for-profit sector.
Inadequate staffing can lead to a range of ramifications for nonprofits. Specifically, a lack of employees and volunteers can restrict or fully prevent nonprofits from providing their services, ultimately blocking them from helping those in need, accomplishing their missions and meeting contractual obligations. This could pose substantial liabilities and associated losses. Staffing shortages also increase the risk of burnout among existing employees, potentially resulting in additional job-related injuries and workers’ compensation claims. Overworked employees and volunteers may also experience decreased morale and be more likely to allege mistreatment in employment litigation, prompting EPL claims.
Given these risks, it’s imperative that nonprofits take steps to attract and retain staff. These steps may include providing improved professional development opportunities, upskilling events, flexible scheduling and mental health and well-being resources. Nonprofit organizations can also expand recruitment efforts by partnering with universities, engaging with retirees or tapping into underrepresented communities. Furthermore, fostering a positive organizational culture can help nonprofits attract and retain employees and volunteers.
Conclusion
Several trends are currently impacting the nonprofit sector, emphasizing the importance of staying informed and adaptive. By tracking these developments and mitigating any associated exposures, nonprofit organizations can maintain operational success and address their unique insurance needs. Contact us today for additional industry-specific risk management tips and coverage solutions.
Ready to get started?
For forward thinking coverage that evolves with you.
Featured insights with industry expertise
Tap into insights designed to help you navigate today’s decisions and tomorrow’s opportunities.

Business Resources
Why small businesses need an annual insurance checkup

Business Resources
How to avoid insurance gaps
Business Resources
Builders risk insurance: Understanding what’s covered
The information provided in this document is intended solely for general informational purposes and is provided with the understanding that neither Huntington, its affiliates nor any other party is engaging in rendering tax, financial, legal, technical or other professional advice or services or endorsing any third-party product or service. Any use of this information should be done only in consultation with a qualified and licensed professional who can take into account all relevant factors and desired outcomes in the context of the facts surrounding your particular circumstances. The information in this document was developed with reasonable care and attention. However, it is possible that some of the information is incomplete, incorrect, or inapplicable to particular circumstances or conditions. NEITHER HUNTINGTON NOR ITS AFFILIATES SHALL BE LIABLE FOR ANY DAMAGES, LOSSES, COSTS OR EXPENSES (DIRECT, CONSEQUENTIAL, SPECIAL, INDIRECT OR OTHERWISE) RESULTING FROM USING, RELYING ON OR ACTING UPON INFORMATION IN THIS DOCUMENT OR THIRD-PARTY RESOURCES IDENTIFIED IN THIS DOCUMENT EVEN IF HUNTINGTON AND/OR ITS AFFILIATES HAVE BEEN ADVISED OF OR FORESEEN THE POSSIBILITY OF SUCH DAMAGES, LOSSES, COSTS OR EXPENSES.
Insurance products are offered by Huntington Insurance, Inc., a licensed agency and a wholly owned subsidiary of Huntington Bancshares Incorporated and underwritten by third party insurance carriers not affiliated with Huntington Insurance, Inc.
Insurance products are: NOT A DEPOSIT • NOT FDIC INSURED • NOT GUARANTEED BY THE BANK • NOT INSURED BY ANY FEDERAL GOVERNMENT AGENCY • MAY LOSE VALUE