1 Michigan Journal of Economics. April 2025. “The Great Wealth Transfer and its Implications for the American Economy.” Accessed April 1, 2026.
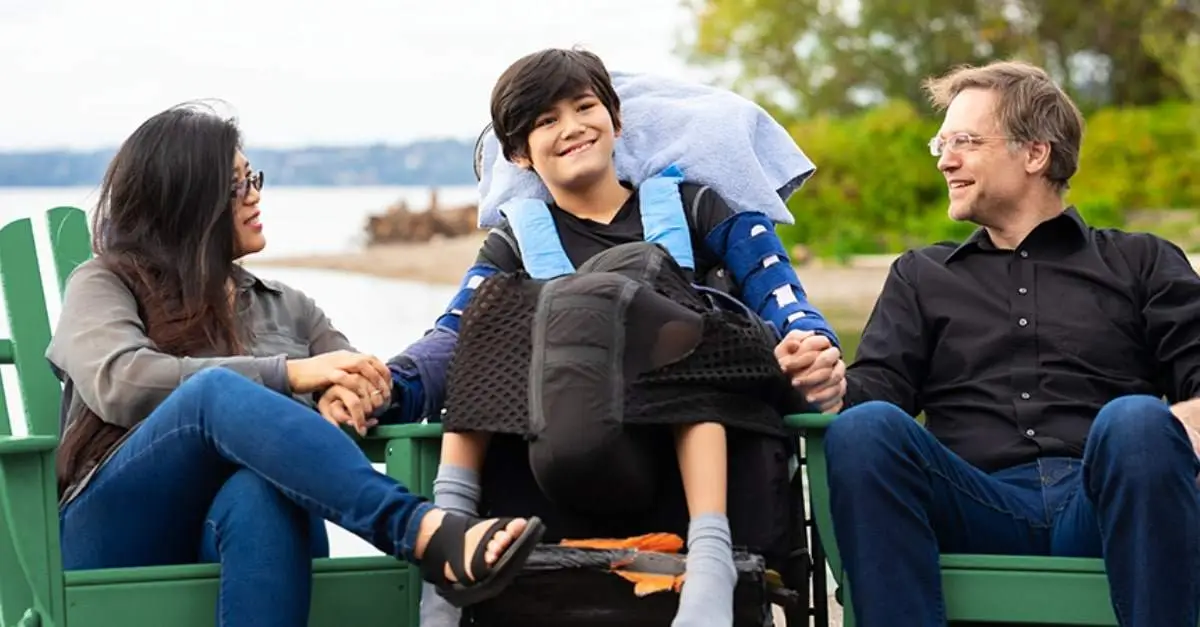
Financial planning for a child with special needs
Jessica Bole, CEPA®, Senior Wealth Strategist
Shaping the financial future for a child with special needs is crucial to ensure they're taken care of even after you're gone. Get started by learning more.
Key takeaways
Plan for incapacity
Protect long-term support
Review as needs change
As a parent, preparing for your own incapacity can be crucial.
Caring for a child with special needs often involves unique considerations and careful preparation for the future. Thoughtful financial planning can help ensure continuity of care, ongoing support and peace of mind.
Many parents prepare for a time when they are no longer alive and able to provide care. However, an equally important consideration is what happens if a parent becomes temporarily or permanently unable to manage decisions due to an illness, injury or cognitive decline. For families of children with mental or physical disabilities, including chronic conditions, this possibility represents an important planning consideration.
Proactive planning can help families address these questions with clarity and intention, rather than under pressure during a crisis.
Talking about what-ifs
Thoughtful planning begins with open and honest conversations about future “what-if” possibilities. Although these conversations are not always easy, they are a critical step in creating a plan that addresses your family’s needs. It’s not just a matter of planning for death or cognitive decline later in life, but also for the possibility of an accident or illness that may limit your ability to make decisions.
When a child with special needs depends on you, proactive planning can help reduce uncertainty and provide the guidance you and your family may need before a situation becomes urgent.
Documenting your wishes
Several essential documents are likely to be part of your special needs financial plan. Powers of attorney for financial and healthcare decisions are important, but one or more trusts may also be needed.
If a child has special needs, a trust can establish what will happen in the case of your death or disability. It designates a trustee who can stand in for you and provides guidance on when and under what circumstances financial support can be provided.
Without a trust and other important documents in place, supervising your child’s care could be left to a court-appointed guardian, whose decisions may follow standard guidelines rather than reflect individual family preferences or routines that matter to the child.
For example, consider the family of a child with a developmental disability whose annual visit to a theme park is the highlight of their year. Their parents established a trust that specifically allocated funds to pay for the trip, as well as the cost of a caregiver and related expenses.
In many cases, a special needs trust (SNT) can be an important part of a child’s care plan. Someone who has mental or physical disabilities may be eligible for government programs, and a SNT can help ensure funds are available for support without disqualifying the child from receiving assistance.
Revisiting your plans
As with all thoughtful financial planning, incapacity planning should be reviewed periodically, making adjustments as children age and as their care and support needs change.
Getting the advice you may need
Establishing the right plan to help support a child with special needs, no matter what happens to their parents, may require legal, financial and in some cases, insurance guidance from experienced professionals.
Learn More
Connect with a wealth advisor
Our advisors foster authentic, lasting relationships through local wealth teams that live and work in your community. If you have a financial question or interest in working with an advisor, let’s get in touch.
Expert guidance and financial insights

Wealth Planning
Generational wealth transfer for the rest of us

Money Management
Tips for taking care of your financial circle

Wealth Planning
Understanding 529 rollover to Roth IRA
Disclosures
Investment, Insurance and Non-deposit Trust products are: NOT A DEPOSIT • NOT FDIC INSURED • NOT GUARANTEED BY THE BANK • NOT INSURED BY ANY FEDERAL GOVERNMENT AGENCY • MAY LOSE VALUE
The Huntington National Bank (“Huntington Bank”) offers a full range of wealth management and financial services through dedicated teams of professionals within the Huntington Private Bank® and Huntington Financial Advisors® as follows:
- Banking solutions, including loans and deposit accounts, are provided by Huntington Bank, Equal Housing Lender and Member FDIC.
- Trust and investment management services are provided by Huntington Bank, a national bank with fiduciary powers.
- Certain insurance products are offered by Huntington Insurance, Inc. and underwritten by third-party insurance carriers not affiliated with Huntington Insurance, Inc.
- Certain investment advisory solutions, securities, and insurance products are provided by Huntington Financial Advisors®, a financial advisory practice of Ameriprise Financial Services, LLC (“Ameriprise”). Huntington Financial Advisors® is the trade name of the investment program offered through Huntington Bank. Certain employees of Huntington Bank provide investment advisory, brokerage, and insurance services, offered by and through Ameriprise in their capacity as registered representatives of Ameriprise. Ameriprise is a registered investment adviser and broker-dealer member of FINRA and SIPC. Ameriprise is not affiliated with Huntington Bank, Huntington Insurance, Inc., or Huntington Bancshares Incorporated. Ameriprise and Huntington Bank partner to provide financial planning services and solutions to clients. Huntington Bank is not an investment client of Ameriprise; however, it receives revenue sharing payments from Ameriprise, which creates a conflict of interest. Details on how we work together can be found on ameriprise.com/sec-disclosure.
Huntington Private Bank® is a federally registered service mark of Huntington Bancshares Incorporated.
Huntington Financial Advisors® is a federally registered service mark of Huntington Bancshares Incorporated and is used under license.
Huntington Bank and Huntington Insurance, Inc. are wholly-owned subsidiaries of Huntington Bancshares Incorporated.
Minimum investment or deposit balance criteria apply with respect to the Huntington Private Bank. Please contact a Huntington Private Bank colleague for more information on eligibility requirements.