If you have previously unsubscribed from Huntington marketing emails, subscribing reaffirms your agreement to receive email. This will not impact servicing email related to account activity. For questions, please consult Huntington’s Privacy and Security policy.
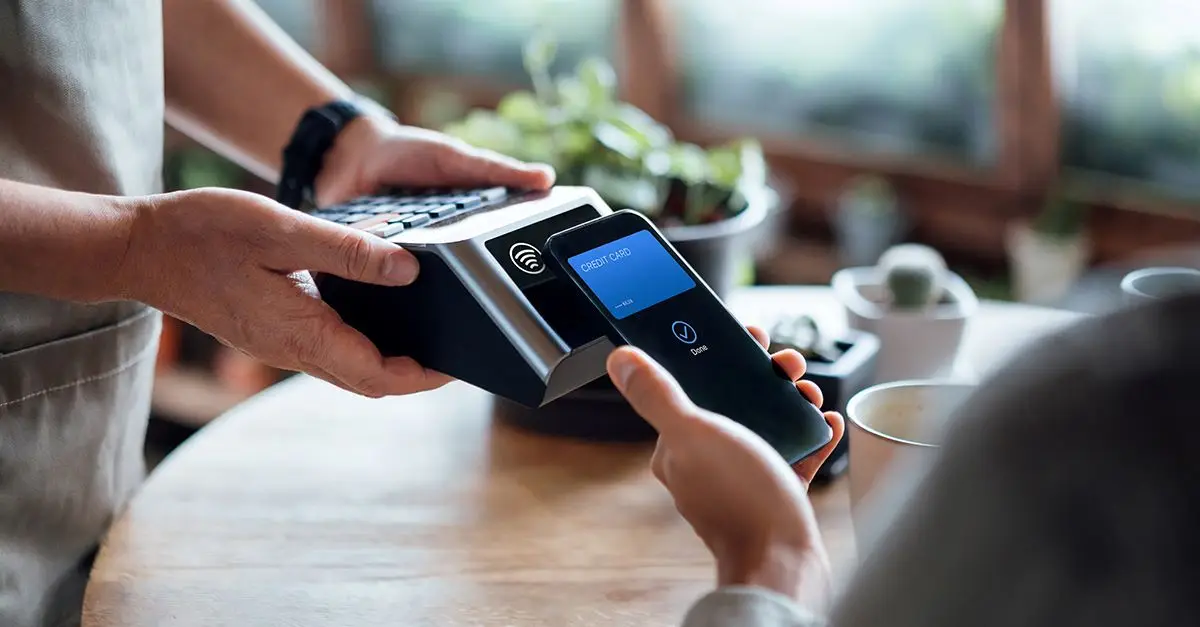
The digital payment revolution: Key trends driving change
By Lucia Sprungle, Director – ChoicePay®, at Huntington Commercial Bank
Payments are rapidly becoming more digital, mobile, and consumer driven. Explore the trends reshaping how people pay, why expectations are changing, and what organizations should consider as digital payment adoption accelerates.
Key takeaways
Consumers now expect easy, flexible payment options
Digital wallet use is growing rapidly
Business sector use cases are evolving
Security is more important than ever
Digital payments have evolved from a convenience into an increasingly important part of the customer experience. Today's consumers expect the same level of speed, flexibility, and accessibility from their payment experiences as they do from other digital interactions. Whether shopping online, paying bills, sending money to friends and family, or receiving reimbursements, consumers want payment options that fit their preferences and lifestyles.
Research shows those expectations continue to rise. According to the Consumer Payments Study conducted for Federal Reserve Financial Services, consumers value payment experiences that are fast, easy to use, and give them confidence1. The study also found that having a choice of payment methods is important to consumers, with more than three-quarters of respondents preferring faster payments.
As digital wallets, contactless payments, instant payment capabilities, and mobile-first financial tools gain momentum, payment preferences are becoming a more important consideration for organizations. Businesses that fail to adapt risk creating friction at critical moments in the customer experience.
Why digital payments are on the rise with consumers
The shift toward digital payments reflects broader changes in how consumers manage their financial lives. According to the most recent FDIC National Survey of U.S. Households, nearly half of banked U.S. households (48.3%) used mobile banking as their primary method of account access2. The FDIC noted that use of mobile banking as a primary access channel has increased nearly ninefold over the past decade.
As mobile financial management has become commonplace, consumers are beginning to expect payments to be just as convenient. Flexibility has become a key driver of payment preferences, with digital wallets allowing users to store multiple payment methods, switch funding sources, and complete transactions across channels through a single interface.
Digital payments are also helping expand access to financial services. According to the FDIC, approximately one-third of unbanked households rely on prepaid cards or nonbank online payment services such as PayPal, Venmo, and Cash App to conduct transactions2.
Why organizations are investing in digital payments
Organizations are recognizing that payments are an important component of the overall customer experience. Consumer expectations continue to influence payment strategy. According to Federal Reserve Financial Services research, 39% of businesses using faster or instant payment methods cited the ability to provide customers with greater flexibility in how they pay and get paid as a key benefit3.
As customer expectations evolve, organizations are reevaluating how customers pay bills, receive refunds, collect reimbursements, and interact with financial transactions throughout the customer journey.
The benefits extend beyond customer satisfaction. Streamlining payment processes through digital methods can help organizations reduce the administrative burden associated with handling checks, clearing payments, and reconciling accounts. In the same Federal Reserve study, 48% of businesses reported using faster or instant payments to help reduce costs3. Faster access to funds can also improve cash flow and accelerate receivables processing. For many organizations, digital payment adoption is becoming both a customer experience initiative and an operational efficiency strategy.

Optimize the accounts receivable process to boost your bottom line
Is an inefficient receivables process holding you back? Learn how to identify opportunities to improve cash collection and reduce costs.
Digital payment trends gaining momentum
Digital payments continue gaining momentum across online and in-person transactions. According to a McKinsey & Company consumer survey, 92% of U.S. consumers reported making some form of digital payment during the previous year4. Digital payments for in-app purchases reached 60% adoption, while in-store digital wallet adoption increased from 19% in 2019 to 28% in 2024.
The influence of digital payments now extends beyond the transaction itself. The same McKinsey survey found that payment platforms are influencing purchasing decisions earlier in the shopping journey. Younger consumers in particular are more likely to begin shopping experiences within digital ecosystems such as buy now, pay later (BNPL) marketplaces and offer aggregators before reaching a merchant's website or mobile app.
These findings demonstrate the increasing digitization of the financial landscape. Consumers increasingly evaluate organizations based on the convenience and flexibility of their overall experience, and payments are often among the most visible interactions. Organizations that understand these changing behaviors may be better positioned to align payment experiences with evolving customer expectations.
How consumers and businesses are using digital payments
Digital payments now support a wide range of financial activities across both consumer and business environments. As adoption continues to grow, organizations are identifying new opportunities to simplify transactions, improve customer experiences, and streamline operations. Evolving regulatory and compliance requirements are creating additional incentives for digital adoption.
Consumer digital payments use trends
Consumers use digital wallets, payment applications, and mobile banking tools to manage both purchasing and money movement activities. According to the latest Federal Reserve's Survey and Diary of Consumer Payment Choice, more than 72% of surveyed U.S. consumers reported using a mobile phone to pay at least once during the 12 months ending in October 2025, and the total share of payments made using a phone increased to 32% of all payments. This increase in mobile payments was largely due to non-bill payments5.
Globally, digital wallet adoption has skyrocketed. A global payments report found that digital wallets are the leading payment method globally, accounting for 56% of eCommerce and 33% of POS value in 20256.
Beyond purchases, consumers are using digital payment tools to:
- Pay bills.
- Transfer money between accounts.
- Send money to friends and family.
- Receive rebates and refunds.
- Access wages and other disbursements more quickly.
Business sector digital payments use trends
Retail
Retail organizations remain at the forefront of payment transformation. More and more consumers rely on digital wallets in both ecommerce and in-store environments, with the latest Federal Reserve payment study data showing 58% of surveyed U.S. consumers used digital wallets to make or receive payments in the past 12 months1.
As adoption grows, retailers should evaluate whether their payment offerings reflect customer preferences. A commissioned Nielsen study found that advertising PayPal at checkout could increase unplanned purchases by 13%, and by as much as 38% for food delivery purchases7.
Organizations that evaluate payments through the lens of consumer preference may be better positioned to reduce friction throughout the purchasing process.
Healthcare
Healthcare organizations have long faced challenges associated with patient billing and reimbursements. New requirements have led to an uptick in patient overpayments, adding pressure to an already overburdened sector.
At the same time, patient expectations are increasingly shaped by experiences outside healthcare. Consumers who can pay bills digitally, receive payment reminders electronically, and obtain reimbursements through convenient methods may perceive the overall financial experience more positively.
As digital payments become more common in everyday life, healthcare organizations have an opportunity to modernize payment experiences while maintaining security and compliance requirements. This can be particularly valuable when offering reimbursement options such as ChoicePay® that allow patients to select their preferred payment method.
Higher Education
Many students are digital natives who regularly use mobile banking, digital wallets, and peer-to-peer payment applications. As a result, expectations around refunds, reimbursements, and other disbursements are being shaped by consumer payment experiences.
Institutions that continue relying heavily on paper-based processes may find their payment experiences out of step with student expectations. Providing secure digital payment options can help align institutional processes with how many students already manage their finances.
Security and compliance in the digital payments landscape
Security remains a top concern for both businesses and consumers as digital payment adoption expands.
Consumers expect their digital convenience to include protection of their financial information. Organizations must balance ease of use with strong security controls. Many digital payment solutions incorporate technologies such as tokenization, encryption, and biometric authentication to help protect payment credentials and limit exposure of sensitive information. These capabilities can provide additional layers of security that are not available with traditional payment methods such as checks or cash.
Emerging technologies such as artificial intelligence and machine learning are also helping organizations strengthen fraud detection and risk monitoring capabilities by identifying unusual behavior and suspicious transaction patterns more efficiently.
As digital payment ecosystems continue to evolve, maintaining trust will remain a critical component of successful adoption.
The future of payments: What comes next?
Digital payments are becoming deeply embedded in how consumers manage money and interact with organizations. As new payment methods emerge, customer preferences will continue to shift. Organizations that proactively evaluate their payment strategy may be better positioned to meet changing customer expectations while supporting business performance.
Learn more about the digital payment transformation and how your business can adopt new payment practices, measure success, and meet evolving needs in this article series. For more information about modernizing payments within your organization, contact our ChoicePay team.
Unlock a new era of payment convenience
Transition to a paperless environment with digital payment processing.
Modernizing payments with digital solutions can help reduce costs and increase customer satisfaction. Huntington’s ChoicePay® is designed to meet the evolving needs of your organization and customers.
Subscribe
Huntington Business Insights
Financial news, insights, and guidance delivered right to your inbox.
Sign up to receive emails about our latest articles, case studies, and events on topics that matter to your business.
Featured insights with industry expertise
Tap into insights designed to help you navigate today’s decisions and tomorrow’s opportunities.

Treasury Management & Payments
Modernizing treasury connectivity through integrations
Treasury Management & Payments
Refining cash segmentation to support decision making

Treasury Management & Payments
How businesses build operational excellence
1 Federal Reserve Financial Services. 2025. “Federal Reserve Payments Insight Brief: Consumer Payments Study.” Accessed September 28, 2026.
2 Federal Deposit Insurance Corporation (FDIC). 2024. “FDIC National Survey of Unbanked and Underbanked Households.” Accessed September 28, 2026.
3 Federal Deposit Insurance Corporation (FDIC). May 2024. “Federal Reserve surveys: U.S. businesses, consumers increasingly adopt faster and instant payment services.” Accessed September 28, 2026.
4 Varadarajan, Roshan, Felicia Tan, Abhinav Sah, Louis Anckaert. October 2024. “State of Consumer Digital Payments in 2024.” McKinsey & Company, 2024. Accessed September 28, 2026.
5 Federal Reserve, Bank of Atlanta. 2026. “2025 Survey and Diary of Consumer Payment Choice: Summary Results.” Accessed September 28, 2026.
6 Global Payments (formerly Worldpay). 2026. “The Global Payments Report: GPR 2026.” Accessed September 28,2026.
7 Paypal. January 2024. “PayPal May Help Drive Conversions, Spend, and Satisfaction, According to Nielsen.” Accessed September 28, 2026.
Apple Pay® is a trademark of Apple Inc., registered in the U.S. and other countries.
The Google logo, Google Wallet and Android are trademarks of Google LLC.
Third-party product, service and business names are trademarks/service marks of their respective owners.
The information provided in this document is intended solely for general informational purposes and is provided with the understanding that neither Huntington, its affiliates nor any other party is engaging in rendering financial, legal, technical or other professional advice or services, or endorsing any third-party product or service. Any use of this information should be done only in consultation with a qualified and licensed professional who can take into account all relevant factors and desired outcomes in the context of the facts surrounding your particular circumstances. The information in this document was developed with reasonable care and attention. However, it is possible that some of the information is incomplete, incorrect, or inapplicable to particular circumstances or conditions. NEITHER HUNTINGTON NOR ITS AFFILIATES SHALL HAVE LIABILITY FOR ANY DAMAGES, LOSSES, COSTS OR EXPENSES (DIRECT, CONSEQUENTIAL, SPECIAL, INDIRECT OR OTHERWISE) RESULTING FROM USING, RELYING ON OR ACTING UPON INFORMATION IN THIS DOCUMENT EVEN IF HUNTINGTON AND/OR ITS AFFILIATES HAVE BEEN ADVISED OF OR FORESEEN THE POSSIBILITY OF SUCH DAMAGES, LOSSES, COSTS OR EXPENSES.
Third-party product, service and business names are trademarks/service marks of their respective owners.