If you have previously unsubscribed from Huntington marketing emails, subscribing reaffirms your agreement to receive email. This will not impact servicing email related to account activity. For questions, please consult Huntington’s Privacy and Security policy.
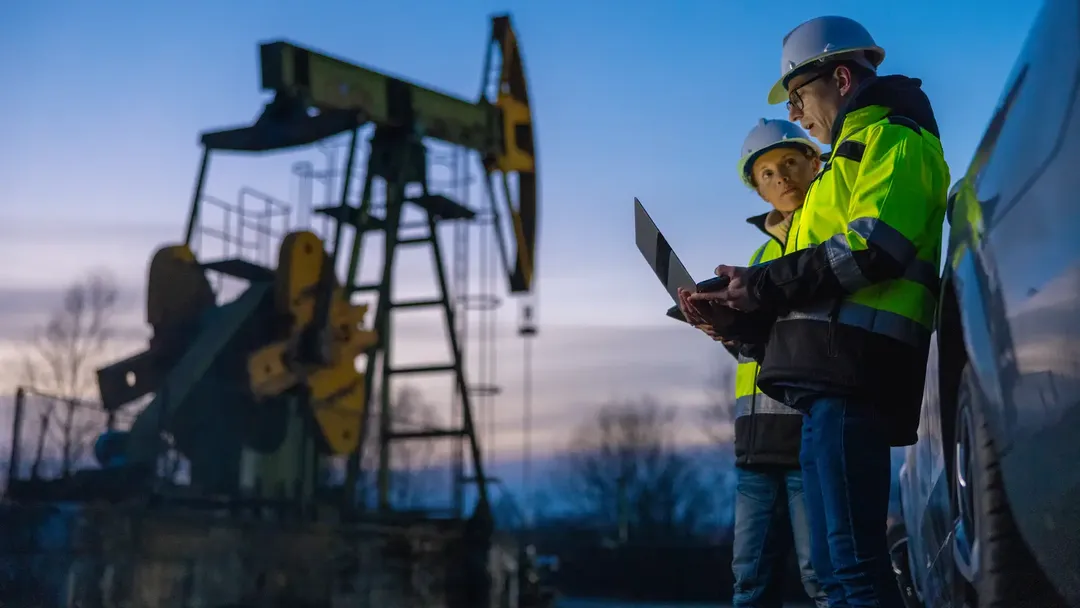
Oil and gas insurance in 2027: What to consider before your next renewal
Justin Townsend, Senior Risk Advisor, Huntington Insurance, Inc.
Changing market conditions may give oil and gas companies more options at their next insurance renewal. Reviewing how operations, risk management practices and coverage needs have changed can help businesses make more informed decisions.
Key takeaways
Look beyond premium
Risk management can make a difference
Review coverage as operations evolve
Oil and gas companies preparing for their next insurance renewal may find more options than they’ve had in recent years. After several challenging years, conditions began improving in late 2025 and continued through 2026. Well-operated businesses are generally seeing renewals ranging from flat to single-digit increases, although auto and excess liability remain more challenging.
That makes the next renewal an opportunity to look beyond premium and ask a broader question: Does your insurance program still reflect your business, its risks and the steps you’re taking to manage them?
Does your current insurance program still fit the business?
Enhanced competition and capacity in the oil and gas insurance marketplace are giving some businesses additional options at renewal. That competition can create an opportunity to look beyond premium and review whether coverage, deductibles and other policy terms still match the company’s operations and risks.
Market conditions can vary by coverage and business type. As a result, companies may want to consider how changes in areas such as commercial auto and property insurance may affect their broader insurance program and total cost of risk.
Businesses change from year to year. Equipment is added, operations expand and relationships with customers or contractors evolve. The insurance program should keep pace with those changes rather than simply carrying last year’s structure into another renewal.
Are insurers seeing the improvements you’ve made?
Managing risk is one part of the renewal process. Making sure insurers understand those efforts is another. For oil and gas companies, insurers may look closely at how businesses manage their fleets, drivers and relationships with contractors. Companies that regularly use subcontractors, for example, can use master service agreements to clearly establish responsibilities and insurance requirements.
Investments in telematics, stronger fleet management or updates to service agreements may affect how insurers view the business. Those improvements need to be clearly communicated before and during the renewal process. Even relatively small changes to a service agreement can sometimes affect an insurer’s willingness to consider the risk. Clearly communicating those improvements can be just as important as making them.
How are you managing fleet risk?
Fleet safety deserves particular attention in oil and gas operations. Roughly 4 in 10 workers who die on the job in oil and gas extraction are killed in highway vehicle incidents, with highway accidents ranking as the industry’s leading cause of worker fatalities1. Auto liability insurance and excess liability coverage continue to be challenging areas for oil and gas companies, making active fleet and driver management an important part of the insurance discussion.
Telematics and dash cameras can provide a clearer record of what happened when an accident occurs. That information can support the claims process and provide useful evidence when a company needs to defend itself.
Installing the technology doesn’t necessarily translate into an automatic insurance discount. Its value comes from putting the information to work by managing drivers, coaching behavior and responding to incidents. Over time, those practices may lead to better outcomes and also help insurers better understand how the company manages its fleet risk.
Have your operations changed?
An insurance renewal is also an opportunity to consider how the business itself has changed. U.S. crude oil production averaged 13.7 million barrels per day during the first half of 2026, up 2% from the same period in 2025, with production forecasted to average a record 13.8 million barrels per day for the full year2.
Changes in commodity prices can influence which assets make economic sense to operate. When oil prices rise, for example, a less productive well that wasn’t economical at lower prices may become viable again. An operator may decide to restart a well that has been inactive for several years. Older shut-in wells often receive additional underwriting attention, particularly for environmental liability and control of well coverage. The broader point applies beyond wells: When operations or assets change, insurance needs may change with them.
Make the most of your next renewal
More favorable market conditions can create opportunities, but renewal should be about more than finding a lower premium. Consider whether your coverage still reflects how the business operates today, what has changed since the previous renewal and whether insurers have a clear picture of the steps you’re taking to manage risk.
Huntington Insurance can help businesses understand what insurers are looking for, identify opportunities to better communicate their risk management practices and evaluate whether coverage continues to reflect their operations.
Contact Huntington Insurance to discuss your organization’s risk management and insurance needs.
Subscribe
Huntington Business Insights
Financial news, insights, and guidance delivered right to your inbox.
Sign up to receive emails about our latest articles, case studies, and events on topics that matter to your business.
Featured insights with industry expertise
Tap into insights designed to help you navigate today’s decisions and tomorrow’s opportunities.

Risk Management
Submitting a cyber insurance claim: Steps to minimize risk and downtime

Risk Management
Healthcare costs are rising. Is your employee benefits provider keeping up?
Risk Management
Overcoming D&O insurance misconceptions: What boards need to know
1 Occupational Safety and Health Administration. “Safety Hazards Associated with Oil and Gas Extraction Activities.” Accessed October 15, 2026.
2 Manning-Pickett, Trinity. September 10, 2026. “United States on track for record crude oil production in 2026.” U.S. Energy Information Administration. Accessed October 15, 2026.
The information provided in this document is intended solely for general informational purposes and is provided with the understanding that neither Huntington, its affiliates nor any other party is engaging in rendering financial, legal, technical or other professional advice or services, or endorsing any third-party product or service. Any use of this information should be done only in consultation with a qualified and licensed professional who can take into account all relevant factors and desired outcomes in the context of the facts surrounding your particular circumstances. The information in this document was developed with reasonable care and attention. However, it is possible that some of the information is incomplete, incorrect, or inapplicable to particular circumstances or conditions. NEITHER HUNTINGTON NOR ITS AFFILIATES SHALL HAVE LIABILITY FOR ANY DAMAGES, LOSSES, COSTS OR EXPENSES (DIRECT, CONSEQUENTIAL, SPECIAL, INDIRECT OR OTHERWISE) RESULTING FROM USING, RELYING ON OR ACTING UPON INFORMATION IN THIS DOCUMENT EVEN IF HUNTINGTON AND/OR ITS AFFILIATES HAVE BEEN ADVISED OF OR FORESEEN THE POSSIBILITY OF SUCH DAMAGES, LOSSES, COSTS OR EXPENSES.
Third-party product, service and business names are trademarks/service marks of their respective owners.